Boeing lost a tenth of its value in a day, on a quarter that was not even a disaster
Revenue rose four percent to 24.19 billion dollars and the loss narrowed to 34 cents a share from 7.47 dollars a year ago. Then Boeing said the 500 jet delivery target is gone, the production ramp slips into next year, and the cash outlook fell billions short of what analysts expected.
New York · October 28, 2026
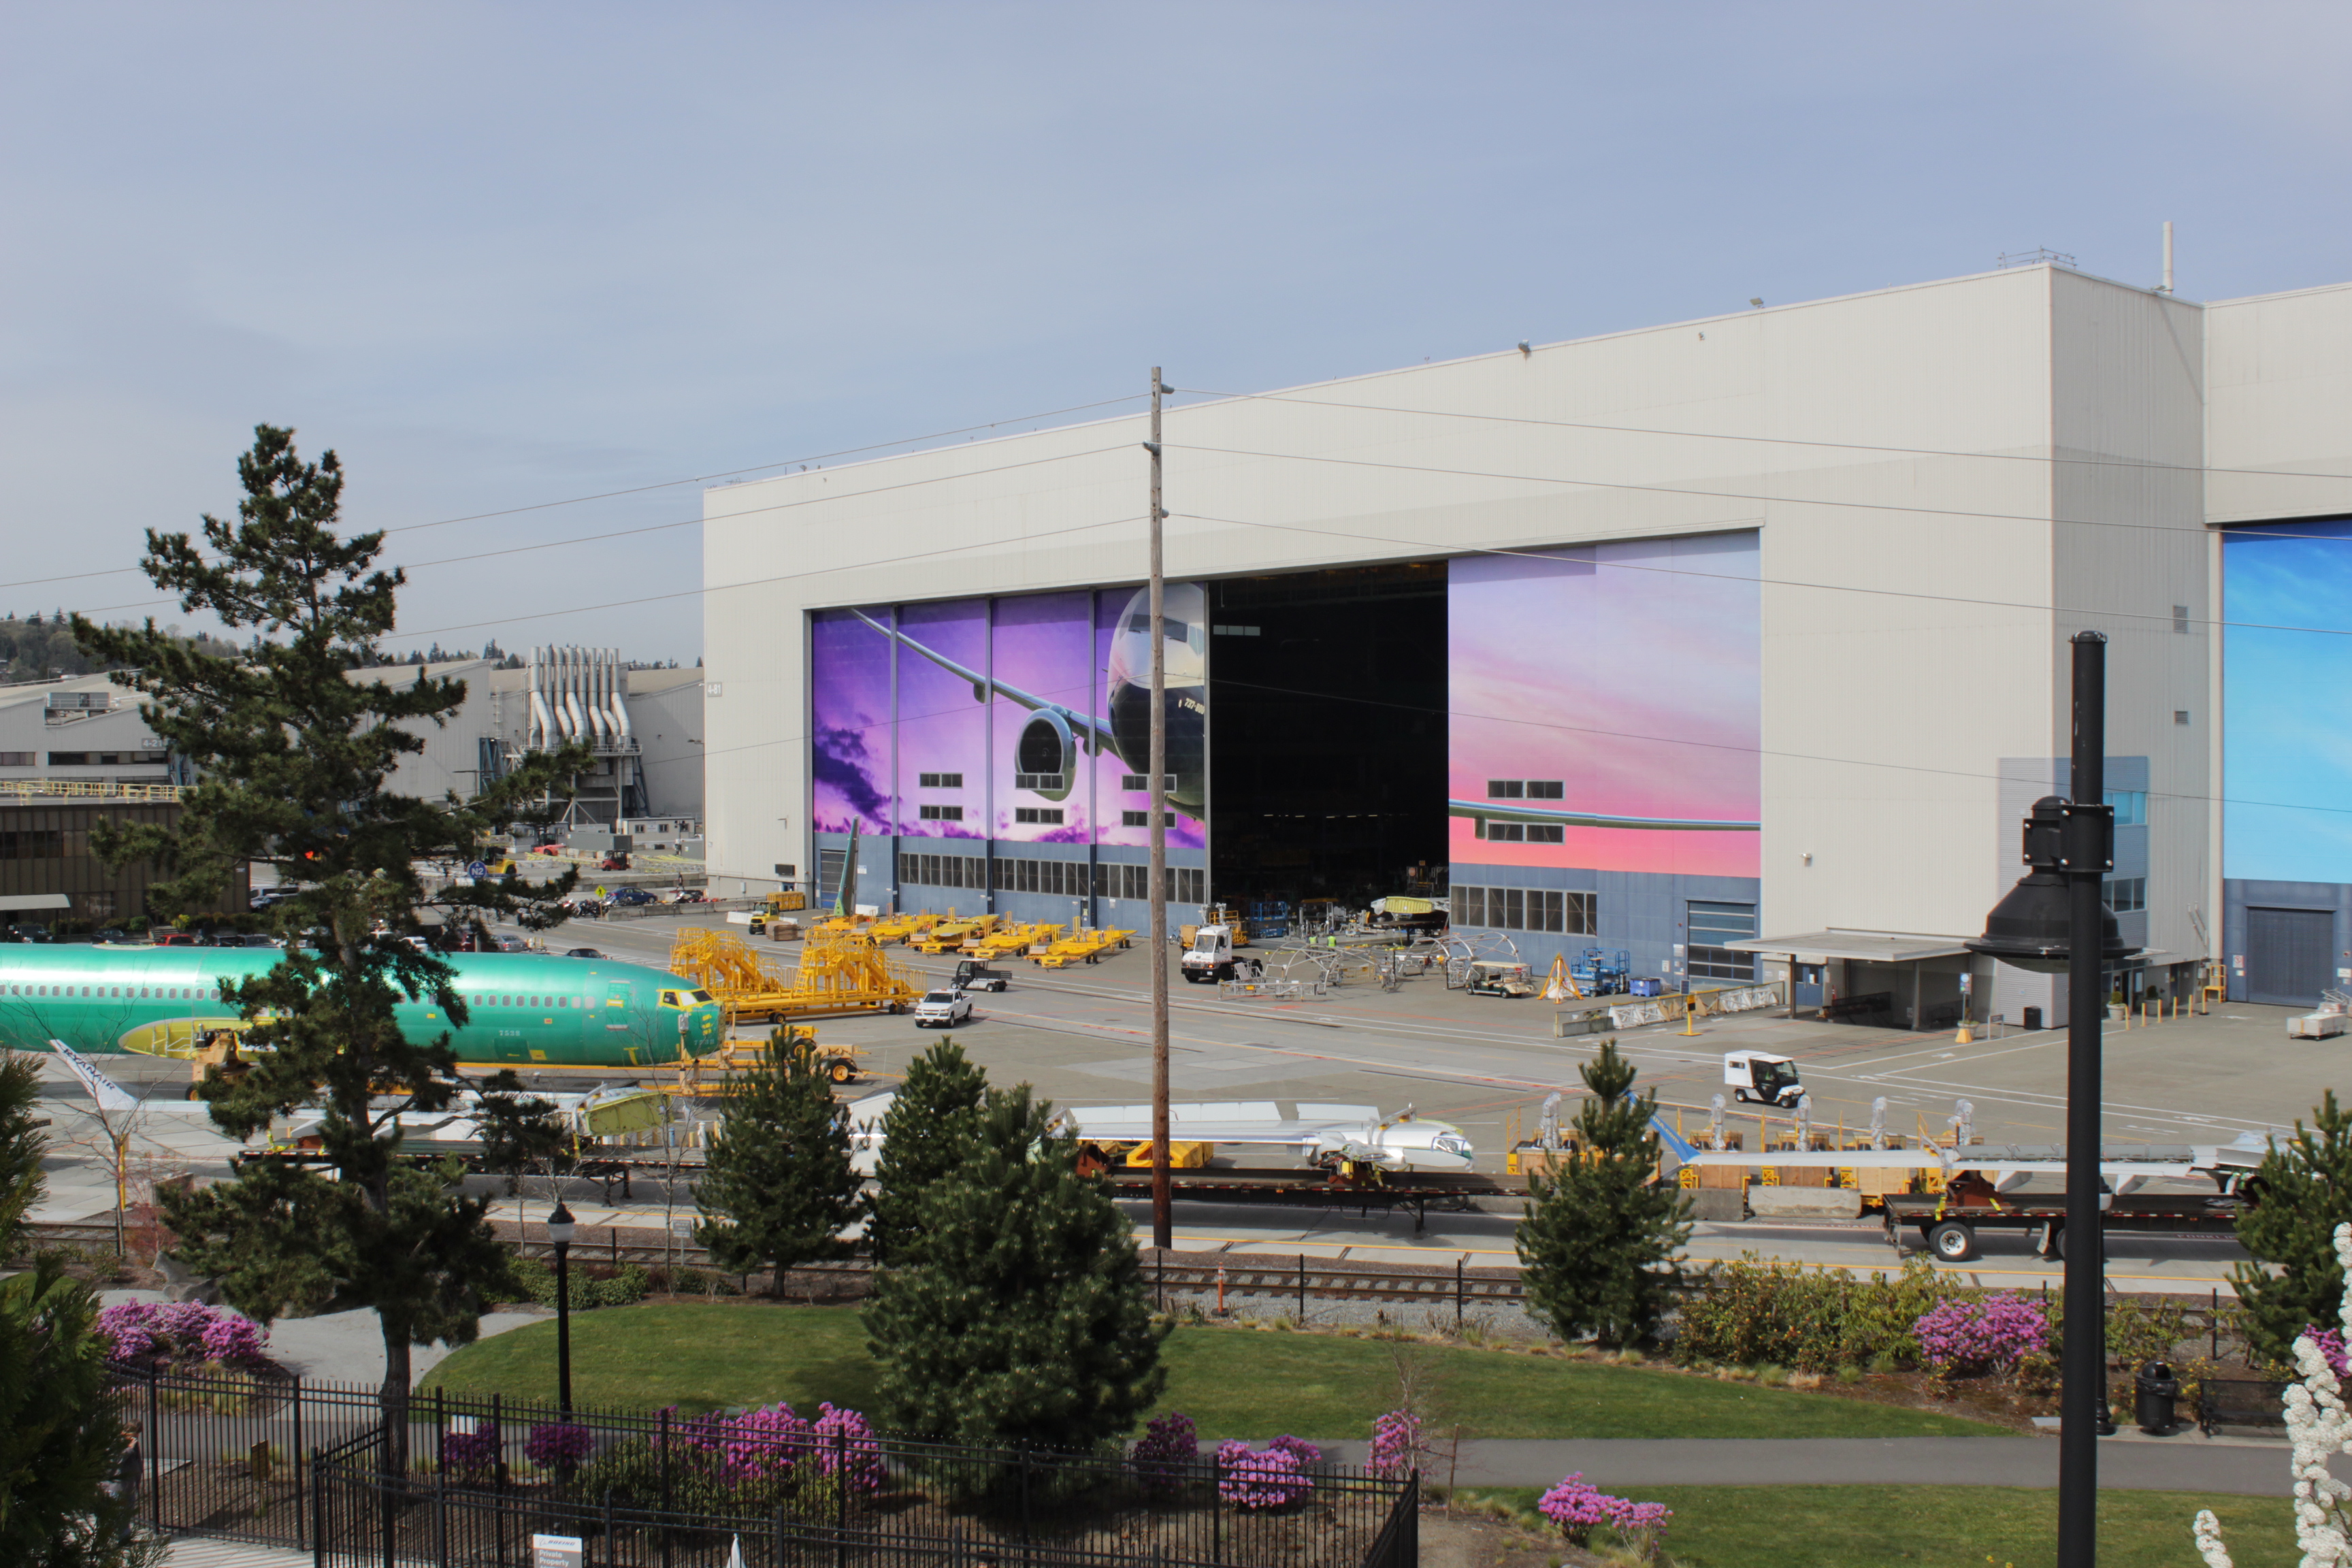
Boeing shares closed on Tuesday at 168.18 dollars, down 10.69 percent from 188.31 dollars the day before, the worst session in more than a year. The fall did not start with the numbers. It started with the conference call, when chief executive Kelly Ortberg explained that the turnaround investors keep pricing in has moved further away again, not because nobody wants Boeing's planes, but because the factories still cannot build them at the pace the plan requires.
Read on its own, the quarter was unremarkable in a way Boeing would once have celebrated. Revenue rose four percent to 24.19 billion dollars, the net loss narrowed to 116 million dollars from 5.34 billion a year earlier, and the core loss came in at 34 cents a share against 7.47 dollars a year ago, though wider than the roughly 21 to 25 cents analysts had expected. Free cash flow was positive at 464 million dollars. Commercial Airplanes still lost money, 697 million dollars on 10.72 billion of revenue, down three percent, while defence revenue rose 15 percent and services rose four percent. Deliveries totalled 161 aircraft in the quarter, up one percent.
What hurt was everything dated next year. Boeing will miss its target of 500 737 MAX deliveries this year. Reaching a steady 47 planes a month, a rate it had aimed for this past summer, now slips into early next year, with 52 a month targeted for the second half of 2027, because wing production is running slower than planned. Cash follows the planes, so the cash outlook moved with it. Boeing guided to about three billion dollars of free cash flow in 2027 against 5.6 billion analysts had counted on, about six billion in 2028 against 9.6 billion expected, and about ten billion only in 2029. Each year of delay in the factory becomes a year of delay in the money, and the market repriced all three years at once.
Set against that is the strangest fact in the whole report. Demand is not the problem at all. Boeing sits on a record backlog of 745 billion dollars, took 300 net orders in the quarter alone and has more than 6,300 commercial aircraft on order. The wider market rose on the same day, which makes the verdict plainer: this was not a selloff Boeing got caught in, it was a judgement on Boeing alone. The planes are sold, years into the future. The entire investment case now rests on a production line in Renton learning to move faster without cutting the corners that put the company here.
Our call is that the discount is now doing two jobs at once, and only one of them is fair. Pricing in slower cash for 2027 and 2028 follows directly from what management said, and investors who trusted the earlier timetable have been burned often enough to demand proof before they pay for a ramp again. But a company with a 745 billion dollar order book does not have a demand problem to solve, it has a throughput problem, and throughput problems, unlike lost customers, can be fixed inside its own walls. That is why every Boeing promise now trades at a discount until the monthly rate actually prints at 47 and holds there. Watch the rate, not the orders. The orders stopped being the question a long time ago.
The Briefing
The day's world, market and sport, measured and in your inbox before breakfast. One email, no noise, free while we build it.
Subscribe by emailSubscribing opens your email app with a note to [email protected]. We never share your address.